
Switzerland
Switzerland introduced Value Added Tax(VAT) in 1995. Switzerland is not part of the European Union, but it does operate a very similar system of VAT. In Switzerland, the VAT is also known as Mehrwertsteuer (MWST), Taxe sur la valeur ajoutée (TVA) or Imposta sul valore aggiunto (IVA).
The official administrative languages of Switzerland are German, French and Italian depending on which Canton/County you are in.
Switzerland VAT Country Guide
Switzerland VAT Registration
Switzerland have set the threshold for both domestic and foreign sellers at 100,000 CHF for mail order companies only( approximately 90k GBP, 105k EUR). The threshold is based on companies selling low value ecommerce goods not exceeding 65 CHF. Once the threshold has been exceeded the company is obligated to register in the Swiss VAT register. Companies can choose to voluntarily register if they are below the threshold.
For other sales in Switzerland the threshold is also 100,000 CHF however it is based on the foreign companies global turnover. Any company exceeding the threshold must register within 30 days.
You are required to register for a Swiss VAT number if you carry out the following activities;
- Importation of goods into Switzerland
- Buying and selling goods within the Swiss territory
- Storing goods in Swiss warehouses
- Organizing events in which the customer pays for a ticket
If the company is a Swiss-established company then they do not require to appoint a fiscal representative. Non-established foreign businesses are required to appoint a fiscal representative who takes responsibility for the submission of VAT returns and payment of VAT.
Businesses registered for VAT are reported in the UID register. Commercial details such as business name, enterprise number, legal status and seat can be found in the commercial register.
Deposit Requirements
For domestic or foreign mail-order companies who meet the requirements for tax liability in Switzerland and must register for VAT they must provide collateral by either means of an unlimited joint and several surety from a bank domiciled in Switzerland or a cash deposit made to the tax authorities equal to 3% of their annual turnover in Switzerland. The deposit should be a minimum of CHF 2,000 and maximum of CHF 250,000. Once the registration is accepted you will be given 20 days to provide either option.
Distance sales of goods
Article 7 Paragraph 3 letter b of the VAT Act (provision for mail-order sales) entered into force on January 1st 2019. Any person making supplies of low value goods (goods with a tax liability less than CHF 5) and achieving a turnover of 100,000 francs must register for VAT purposes in Switzerland.
Until December 31st 2023
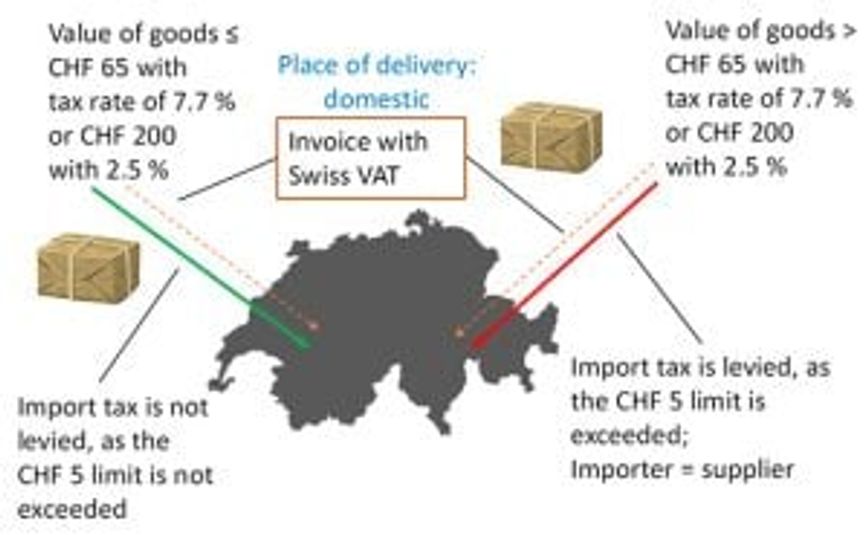
The threshold for low value goods is changing due to the increase in Swiss VAT rates. The above diagram shows the current treatment, if mail-order goods imported are equal to or below a value of CHF 65 and taxed at 7.7% or CHF 200 at 2.5% then import tax is not levied as the threshold of CHF 5 (tax owed) has not been exceeded.
If the value of goods exceeds the thresholds then import tax is levied.
From January 1st 2024
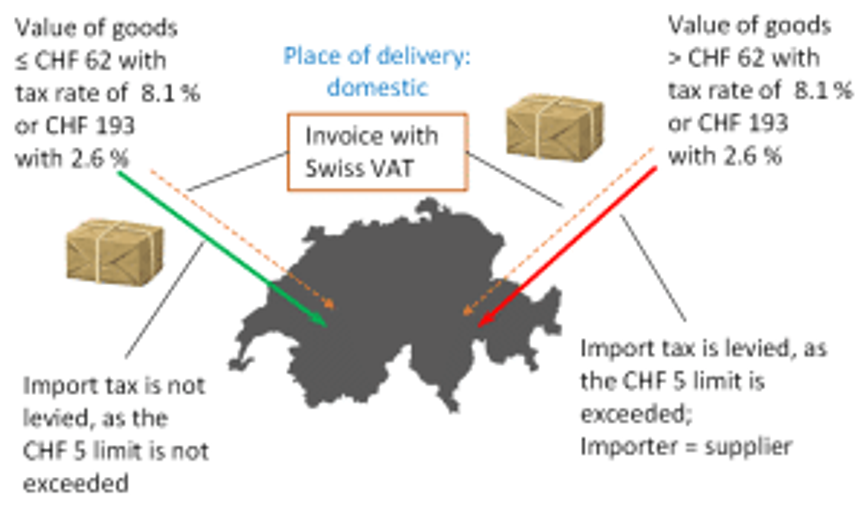
The above diagram shows the current treatment, if mail-order goods imported are equal to or below a value of CHF 62 and taxed at 8.1% or CHF 193 at 2.6% then import tax is not levied as the threshold of CHF 5 (tax owed) has not been exceeded.
If the value of goods exceeds the thresholds then import tax is levied.
Switzerland VAT Filing Frequency & Deadlines
Swiss VAT returns are filed quarterly and must be submitted with the VAT paid within 60 days after the period ends. A NIL return must be submitted if there is nothing to report
| Reporting Period | Deadline for payment and submission |
|---|---|
| 1st January to 31st March | 30th May |
| 1st April to 30th June | 29th August |
| 1st July to 30th September | 29th November |
| 1st October to 31st December | 28th February |
VAT Refunds non-resident
If a foreign company is looking to recover VAT incurred in Switzerland then they can do so via a VAT reclaim however their home country must have a reciprocity agreement with Switzerland. To recover the funds the company must appoint a fiscal representative. Claims can be made once per annum before 30 June the following year and must exceed 500 CHF in value.
Types of Swiss VAT The Switzerland VAT rates are due to increase as of 01.01.2024, below are the new rates.
| Rate | Type |
|---|---|
| 8.1% | Standard |
| 3.8% | Reduced |
| 2.6% | Reduced |
| 0% | Zero |
| 0% | Exempt |
Switzerland VAT Rates
8.1% Standard - All goods or services not included in the reduced rate tables. 3.8 % Reduced - Hotel Accommodation Services (including breakfast services). 2.6% Reduced - Water distributed through pipes, Foods items and additives, excluding alcoholic beverages. Not applicable to catered food but does apply to takeaway, delivery or sole through vending machines. Livestock such as cattle, poultry and fish. Corn, seeds, planting roots, bulbs, live plants, scions, cut flowers, branches, and similar items used for arrangements, bouquets and wreaths. Animal feed, silage acidity, and scatterings used for animals, fertilizers, pesticides, mulch and other vegetation employed as covering materials, medications, newspapers, magazines and books (printed or electronic) excluding advertising materials, services provided by radio and television stations, excluding commercial services, cultural services including entrance fees for cultural events, charges for sporting events and the supply of works by creators such as authors, composers, painters and filmmakers. Agricultural supplies associated with land cultivation directly related to initial production or cultivation 0% Zero - Goods that are directly exported abroad without being used or exploited in Switzerland including chain transaction involving multiple suppliers. Supplies of goods for use or exploitation abroad, such as leasing or chartering, if the goods are transported directly abroad and predominantly used abroad by the recipient. Goods that have been subject to customs control in Switzerland due to transit, customs warehousing, temporary admission, inward processing, or storage in a bonded warehouse. Movement of goods abroad or arrangements for such movement that are unrelated to a supply of goods. Transport or dispatch of goods in connection with importation or exportation under Swiss customs law. Provision of transport service and related logistics activities abroad or in connection with goods under Swiss customs control. Supply of aircraft to airlines engaged in commercial air transport and charter business, with turnovers from international flights exceeding those from domestic traffic. This exemption also applies to certain services provided to qualifying airlines. Services of intermediaries acting on behalf of others, provided the underlying supply is either exempt with the right to recover input VAT or exclusively carried out abroad. Services provided by travel agents and event organizers in their own name, when they utilize supplies of goods and services from third parties that are provided abroad. International air, bus and rail traffic which may be exempt with the right to recover input VAT to ensure competition neutrality. Domestic supplies of goods that are exported in tourist traffic under specific conditions determined by the government. 0% Exempt - Postal services, health and welfare services. supplies performed by social assistance and social security institutions, supplies closely related to education and cultural development of young people(up to age 25) by charitable youth exchange organizations. Supplies related to child and youth care, supplies in field and education. cultural services ,sports, sport competitions and physical education and sales of works of art by the creators and services provided by publishers.
Get Help
We Will Beat Any Like for Like Quote
All of our packages include registration and VAT returns, plus other additional services
Get in touchThe solution to your VAT problems is just a click away
VAT Registration & Filings
Unlock your sales potential with our bespoke VAT registration and filings services. Our team is ready to identify your VAT obligations allowing your business to expand across the world with a dedicated team beside you.
Leave the complexities to us, our professional team provide a seamlessly fast registration service and help you keep on top of the various filing deadlines so you can keep on top of what matters most.
Import/one stop shop
The two simplification schemes allow for both EU and non-EU businesses to lower the cost of VAT compliance and report multiple transactions using only one registration.
Enrolling in the schemes allows businesses to charge the correct VAT rate of each European country without the need to register for VAT in every member state.
The One Stop Shop and Import One Stop shop have set requirements for businesses to follow to stay compliant, find out more in our service guides.
fiscal representation
When a non-European business trades with the EU, some member states impose the need for a fiscal representative to be appointed for registration, filing, imports or VAT reclaims depending on the various EU rules.
VAT Digital is a recognised and certified European Fiscal Representative allowing for our non-EU clients to trade freely with the EU. This enables a lot of benefits for businesses when registering and importing goods to the European Union.
VAT refunds
Selling internationally can be very profitable but also increase the burden of expenditure for businesses. VAT expenses on goods, services and other operations outside of your home country can be difficult to recover due to the lack of registration or non-compliance.
VAT Digitals specialist team can help identify where VAT can be recovered and process a reclaim to ensure your business is maximizing its profits.
Frequently Asked Questions
How long does it take to receive a VAT number in Switzerland?
It takes approximately 60 days from registration start to finish depending on how quickly the company pays the deposit
Do I need a fiscal representative?
All companies not domiciled in Switzerland are required to register for VAT through a fiscal representative.
Does the threshold apply to the consignment or item?
The mail-order threshold applies to the item and not the full consignment, therefore it is possible multiple items below the threshold can be sent to one customer. This can also simplify customs declarations allowing all orders to different customs being submitted on 1 declaration.
What if the items exceed the mail-order threshold?
Any item that does not comply with the threshold will incur import VAT at border and will be required to be paid by the mail-order company before clearance is approved. Companies can open a CSP account to simplify the procedure
What is a CSP account?
A CSP account makes it easier for mail-order companies to process transactions allowing the customs procedure to be cashless. The funds for VAT payments can be taken directly from the companies CSP account for a seamless customs clearance.
Related Articles
-

EU VAT Rate Increases for 2024
Read more
Client Reviews
Hear from 1000’s of happy customers
-
Hayley, Soterra Limited
Rated 5 out of 5
We have used VAT Digital now for 4 years and they have been instrumental in helping us build our business. They are always helpful as well as prompt to answer any queries and with a wealth of knowledge. I would have no hesitation in recommending them.
-
Jess, Crumbs and Doilies
Rated 5 out of 5
As a small business I found navigating how to register for IOSS incredibly daunting and confusing until I found VAT Digital. VAT Digital enabled my understanding, provided excellent advice and the onboarding process was simple. I would highly recommend VAT Digital and their services
-
Tony, Eglo UK
Rated 5 out of 5
I use VAT Digital as our agent for VAT in both Germany and Ireland – including setting us up in Ireland. The service we receive is always first class – including timely reminders to submit data when necessary. Whenever I’ve had queries on the correct treatment of particular items they are always answered promptly and in detail.
-
Tarun, Basaho
Rated 5 out of 5
Efficient and streamlined service
I’ve been using VAT digital for 3 years now for all my EU VAT filings. I was with a bigger firm before them and I am very satisfied with the switch. They are very helpful, responsive (this was a major requirement for me) and accurate. Their prices are in line with the market or a little lower. Recommended!